Your Local Non-QM Mortgage
Specialist
States Licensed in Pensylvania, Florida and Iowa
Home and investment property loans for self-employed borrowers,
real estate investors, and anyone the big banks turn away.
Personalized Non-QM Experience
Robert Love specializes in Non-QM lending, the loan products designed for borrowers who do not fit the conventional mold. Whether you are self-employed, paid through 1099s, growing a real estate portfolio, or rebuilding after a past credit event, we shop multiple wholesale lenders to find the program and rate that fit your actual financial picture.
Tax returns that do not tell your full story should never cost you the property you want. We qualify borrowers using bank statements, rental income, assets, and other common-sense documentation, all backed by wholesale pricing and technology that keeps the process fast and transparent.
Trust a specialist who focuses on the loans other lenders avoid. Let us help you close on your next home or investment property.
The Non-QM Loan Process
Get Pre-Qualified Talk with a
Non-QM specialist
We match you to the right program and show you what you qualify for, with no tax returns required for many of our products.
Find Your Property
Whether it is your next home or an investment property, work with a trusted real estate agent to find the right fit. DSCR and investor purchases are welcome.
Submit Your Application
Complete your application and let us guide you through underwriting. We handle the heavy lifting and keep you updated all the way to closing.
Don't take my word for it
Non-QM Programs
Mortgage solutions built for self-employed borrowers, investors, and complex financial situations, right here in Panama City Beach, Florida.
Loan Options That Actually Fit You
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Bank Statement Loans
DSCR Loans (Investor Loans)
Equity Xcellarator Loan
Reverse Mortgage
Conventional Loan
FHA Loan
VA Loan
USDA Loan
Frequently Asked Questions
What is a Non-QM loan?
Non-QM stands for Non-Qualified Mortgage. These loans do not follow the strict documentation rules of conventional mortgages, which makes them a fit for self-employed borrowers, investors, and others with non-traditional income. Non-QM does not mean high risk; it means flexible qualification.
Can I get a mortgage if I'm self-employed?
Yes. Many of our self-employed clients qualify using bank statements or a profit and loss statement instead of tax returns, so business write-offs do not work against you.
Can I qualify using my bank statements instead of tax returns?
For most of our bank statement programs, yes. We review 12 to 24 months of deposits to calculate your qualifying income. No tax returns or W-2s needed.
Can I get a loan based on my rental property's income?
Yes, through a DSCR loan. We qualify the loan based on whether the property's rent covers the payment, so your personal income often is not part of the equation.
Can I get a mortgage after a recent bankruptcy or foreclosure?
Often, yes. Several Non-QM programs allow financing with little or no waiting period after a credit event, while conventional loans may require years.
Are Non-QM rates higher than conventional rates?
Non-QM rates are typically a bit higher because the qualification is more flexible. For many borrowers, access to financing now outweighs waiting, and we shop multiple lenders to secure the most competitive pricing available for your profile.
How much down payment do I need for a Non-QM loan?
Down payment requirements vary by program and credit profile and are generally higher than minimum conventional options. We will review your scenario and show you the exact figure during your qualification review.
Can foreign nationals buy property in the US?
Yes. Our foreign national programs help non-US citizens purchase a home or investment property, often without US credit or income documentation.
Can I refinance an investment property or take cash out?
Yes. We offer rate-and-term and cash-out refinancing on investment and non-owner-occupied properties through our DSCR and investor programs.
How long does a Non-QM loan take to close?
Timelines vary, but many Non-QM loans close within a few weeks. Because we use wholesale lenders and streamlined documentation, the process is often faster than borrowers expect.
Most Recent Blog Updates
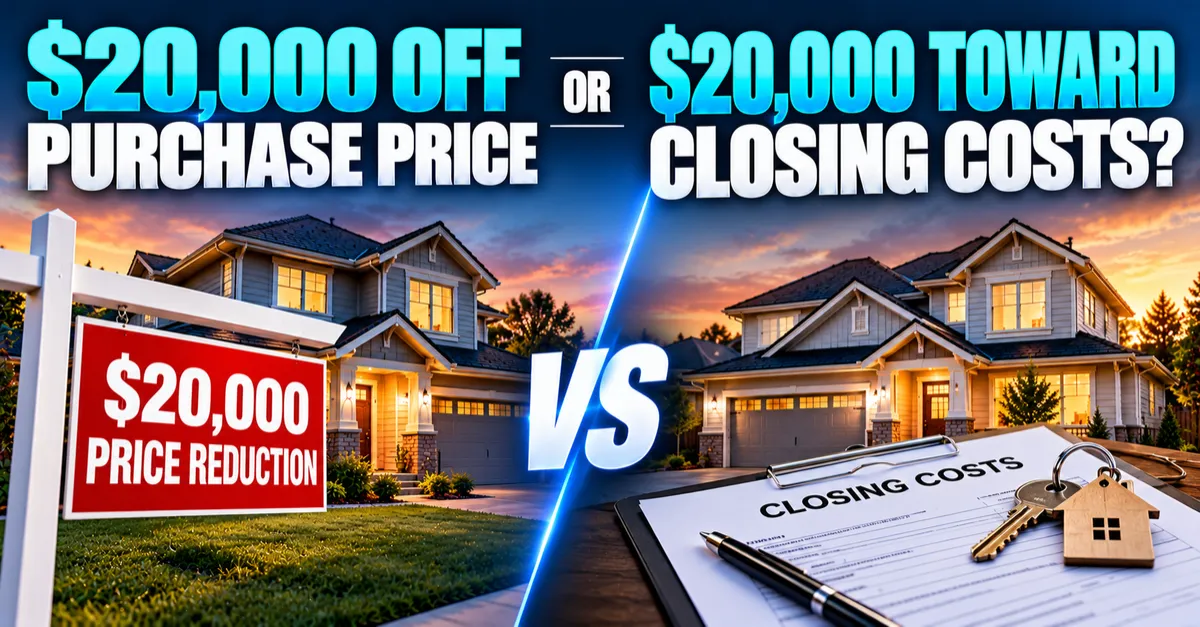
$20,000 Price Reduction or $20,000 Seller Credit: Which Is Smarter? With Robert Love
A Question Most Buyers Answer Too Quickly
Would you rather have $20,000 off the purchase price of a home or $20,000 toward your closing costs? Most buyers automatically choose the price reduction. Robert Love says that instinct might not be the smartest financial decision, and the right answer depends on how your loan is structured and what you need most from the deal.
What a Price Reduction Does
A $20,000 price reduction lowers the amount you are financing. That can reduce your monthly payment, and it also lowers your loan balance from day one. For many buyers it feels like the most straightforward win because the savings show up directly in the purchase price.
What a Seller Credit Can Do
A $20,000 seller credit, when permitted by your loan program, can be put to work in a different way. It can cover closing costs, or it can help buy down your mortgage rate. Depending on your financing, that could improve your monthly cash flow or reduce the amount of cash you need to bring to closing. For buyers who are stretching to cover upfront costs, that flexibility can matter just as much as a lower price.
Which Option Creates the Greatest Benefit
The key is understanding which option produces the greatest financial benefit for your specific situation. Your loan type, your down payment, your cash reserves, and how long you plan to keep the home all influence the answer. Limits on seller credits also vary by loan program, so it is important to confirm what is allowed before you negotiate.
Strategy, Not Just Approval
Robert believes mortgage financing should be about strategy, not simply getting approved. Before negotiating your next home purchase, reach out to Robert Love and compare the numbers side by side so you can choose the option that works hardest for you.
Sources
ConsumerFinancialProtectionBureau.gov
Fanniemae.com
Freddiemac.com
HUD.gov
Investopedia.com

Mortgage Calculator
Estimate your monthly payment and see how a Non-QM loan could
work for your home or investment property.
| Year | Interest | Principal | Balance |
|---|

Quick Links
About Us
Blogs
Programs
