Your Local Non-QM Mortgage
Specialist
States Licensed in Pensylvania, Florida and Iowa
Home and investment property loans for self-employed borrowers,
real estate investors, and anyone the big banks turn away.
Personalized Non-QM Experience
Robert Love specializes in Non-QM lending, the loan products designed for borrowers who do not fit the conventional mold. Whether you are self-employed, paid through 1099s, growing a real estate portfolio, or rebuilding after a past credit event, we shop multiple wholesale lenders to find the program and rate that fit your actual financial picture.
Tax returns that do not tell your full story should never cost you the property you want. We qualify borrowers using bank statements, rental income, assets, and other common-sense documentation, all backed by wholesale pricing and technology that keeps the process fast and transparent.
Trust a specialist who focuses on the loans other lenders avoid. Let us help you close on your next home or investment property.
The Non-QM Loan Process
Get Pre-Qualified Talk with a
Non-QM specialist
We match you to the right program and show you what you qualify for, with no tax returns required for many of our products.
Find Your Property
Whether it is your next home or an investment property, work with a trusted real estate agent to find the right fit. DSCR and investor purchases are welcome.
Submit Your Application
Complete your application and let us guide you through underwriting. We handle the heavy lifting and keep you updated all the way to closing.
Don't take my word for it
Non-QM Programs
Mortgage solutions built for self-employed borrowers, investors, and complex financial situations, right here in Panama City Beach, Florida.
Loan Options That Actually Fit You
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Bank Statement Loans
DSCR Loans (Investor Loans)
Equity Xcellarator Loan
Reverse Mortgage
Frequently Asked Questions
What is a Non-QM loan?
Non-QM stands for Non-Qualified Mortgage. These loans do not follow the strict documentation rules of conventional mortgages, which makes them a fit for self-employed borrowers, investors, and others with non-traditional income. Non-QM does not mean high risk; it means flexible qualification.
Can I get a mortgage if I'm self-employed?
Yes. Many of our self-employed clients qualify using bank statements or a profit and loss statement instead of tax returns, so business write-offs do not work against you.
Can I qualify using my bank statements instead of tax returns?
For most of our bank statement programs, yes. We review 12 to 24 months of deposits to calculate your qualifying income. No tax returns or W-2s needed.
Can I get a loan based on my rental property's income?
Yes, through a DSCR loan. We qualify the loan based on whether the property's rent covers the payment, so your personal income often is not part of the equation.
Can I get a mortgage after a recent bankruptcy or foreclosure?
Often, yes. Several Non-QM programs allow financing with little or no waiting period after a credit event, while conventional loans may require years.
Are Non-QM rates higher than conventional rates?
Non-QM rates are typically a bit higher because the qualification is more flexible. For many borrowers, access to financing now outweighs waiting, and we shop multiple lenders to secure the most competitive pricing available for your profile.
How much down payment do I need for a Non-QM loan?
Down payment requirements vary by program and credit profile and are generally higher than minimum conventional options. We will review your scenario and show you the exact figure during your qualification review.
Can foreign nationals buy property in the US?
Yes. Our foreign national programs help non-US citizens purchase a home or investment property, often without US credit or income documentation.
Can I refinance an investment property or take cash out?
Yes. We offer rate-and-term and cash-out refinancing on investment and non-owner-occupied properties through our DSCR and investor programs.
How long does a Non-QM loan take to close?
Timelines vary, but many Non-QM loans close within a few weeks. Because we use wholesale lenders and streamlined documentation, the process is often faster than borrowers expect.
Most Recent Blog Updates
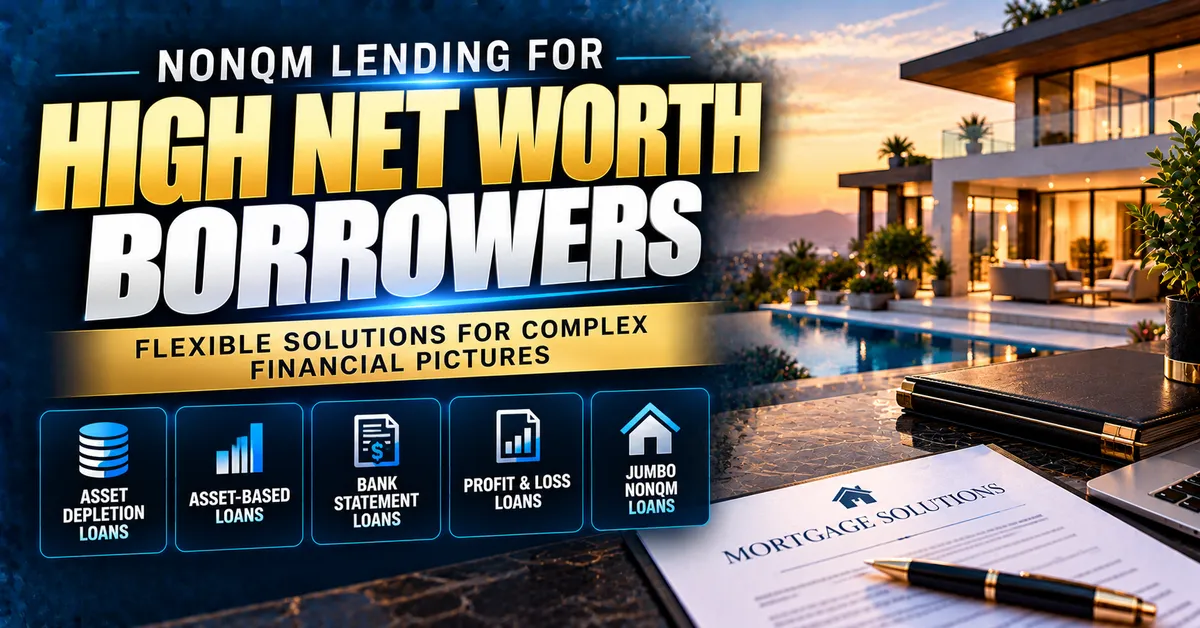
High Net Worth Borrowers With Complex Income Structures Have Better Loan Options Than They Realize
The Lending Gap That Leaves Successful People Without Good Answers
There is a frustrating pattern that Robert Love sees consistently. Borrowers with significant wealth, strong cash flow, and sophisticated financial structures find themselves facing mortgage denials or complications that make no sense given their actual financial position. The problem is never their ability to repay. The problem is that the standard qualification framework was not built for how they earn and hold their money.
Non-QM lending exists precisely to solve this problem and Robert Love works with high net worth borrowers specifically because this is where the right program makes an enormous difference.
The Income Structures That Traditional Lenders Cannot Process
K-1 income from partnerships and S-corporations. Deferred compensation arrangements that distribute income on a different timeline than standard employment. Stock-based compensation that varies year to year and does not arrive on a pay stub. Multiple business entities with income flowing through different structures. Real estate holdings with depreciation that reduces taxable income on paper while actual cash flow remains strong. Diversified investment accounts generating income through distributions and dividends.
Any one of these creates friction in conventional underwriting. Several of them together can make a standard mortgage approval nearly impossible for a borrower whose financial position is genuinely exceptional. The qualification method is the problem not the borrower.
What Non-QM Programs Actually Offer
Asset depletion loans calculate qualifying income by dividing liquid assets by the loan term creating a monthly income equivalent from wealth that already exists. Asset-based loans apply similar logic to qualify borrowers whose balance sheet is the clearest indicator of their strength. Bank statement programs evaluate actual cash deposits over twelve or twenty-four months rather than taxable net income. Profit and loss loans use CPA-prepared statements to document business income directly. Jumbo non-QM options extend these flexible qualification frameworks to higher loan amounts that high net worth borrowers in premium markets frequently require.
Each program addresses a specific documentation challenge with a framework designed for that specific borrower type. The result is qualification based on real financial strength rather than a simplified version of it that leaves substantial wealth unrecognized.
What the Private Consultation With Robert Love Looks Like
Robert takes the time to understand every layer of the financial picture before recommending any program or structure. The goal is a strategy that fits the borrower's actual goals with total clarity whether that is a primary residence, a second home, or an investment property that fits a broader wealth-building plan.
Text, call, or DM Robert Love anytime at 515-805-8870 for a private consultation. Follow along for more strategies that help you make smart moves with your money.
Sources
ConsumerFinancialProtectionBureau.gov
MortgageNewsDaily.com
NationalMortgageProfessional.com
FannieMae.com
Investopedia.com

Mortgage Calculator
Estimate your monthly payment and see how a Non-QM loan could
work for your home or investment property.
| Year | Interest | Principal | Balance |
|---|

Quick Links
About Us
Blogs
Programs
