Your Local Non-QM Mortgage
Specialist
States Licensed in Pensylvania, Florida and Iowa
Home and investment property loans for self-employed borrowers,
real estate investors, and anyone the big banks turn away.
Personalized Non-QM Experience
Robert Love specializes in Non-QM lending, the loan products designed for borrowers who do not fit the conventional mold. Whether you are self-employed, paid through 1099s, growing a real estate portfolio, or rebuilding after a past credit event, we shop multiple wholesale lenders to find the program and rate that fit your actual financial picture.
Tax returns that do not tell your full story should never cost you the property you want. We qualify borrowers using bank statements, rental income, assets, and other common-sense documentation, all backed by wholesale pricing and technology that keeps the process fast and transparent.
Trust a specialist who focuses on the loans other lenders avoid. Let us help you close on your next home or investment property.
The Non-QM Loan Process
Get Pre-Qualified Talk with a
Non-QM specialist
We match you to the right program and show you what you qualify for, with no tax returns required for many of our products.
Find Your Property
Whether it is your next home or an investment property, work with a trusted real estate agent to find the right fit. DSCR and investor purchases are welcome.
Submit Your Application
Complete your application and let us guide you through underwriting. We handle the heavy lifting and keep you updated all the way to closing.
Don't take my word for it
Non-QM Programs
Mortgage solutions built for self-employed borrowers, investors, and complex financial situations, right here in Panama City Beach, Florida.
Loan Options That Actually Fit You
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Bank Statement Loans
DSCR Loans (Investor Loans)
Equity Xcellarator Loan
Reverse Mortgage
Frequently Asked Questions
What is a Non-QM loan?
Non-QM stands for Non-Qualified Mortgage. These loans do not follow the strict documentation rules of conventional mortgages, which makes them a fit for self-employed borrowers, investors, and others with non-traditional income. Non-QM does not mean high risk; it means flexible qualification.
Can I get a mortgage if I'm self-employed?
Yes. Many of our self-employed clients qualify using bank statements or a profit and loss statement instead of tax returns, so business write-offs do not work against you.
Can I qualify using my bank statements instead of tax returns?
For most of our bank statement programs, yes. We review 12 to 24 months of deposits to calculate your qualifying income. No tax returns or W-2s needed.
Can I get a loan based on my rental property's income?
Yes, through a DSCR loan. We qualify the loan based on whether the property's rent covers the payment, so your personal income often is not part of the equation.
Can I get a mortgage after a recent bankruptcy or foreclosure?
Often, yes. Several Non-QM programs allow financing with little or no waiting period after a credit event, while conventional loans may require years.
Are Non-QM rates higher than conventional rates?
Non-QM rates are typically a bit higher because the qualification is more flexible. For many borrowers, access to financing now outweighs waiting, and we shop multiple lenders to secure the most competitive pricing available for your profile.
How much down payment do I need for a Non-QM loan?
Down payment requirements vary by program and credit profile and are generally higher than minimum conventional options. We will review your scenario and show you the exact figure during your qualification review.
Can foreign nationals buy property in the US?
Yes. Our foreign national programs help non-US citizens purchase a home or investment property, often without US credit or income documentation.
Can I refinance an investment property or take cash out?
Yes. We offer rate-and-term and cash-out refinancing on investment and non-owner-occupied properties through our DSCR and investor programs.
How long does a Non-QM loan take to close?
Timelines vary, but many Non-QM loans close within a few weeks. Because we use wholesale lenders and streamlined documentation, the process is often faster than borrowers expect.
Most Recent Blog Updates
If You Are Thinking About Buying a Home Here Is the One Thing You Should Not Do First
Looking at homes before knowing your numbers leads to heartbreak. Nicole and Robert Love explain the right first step. ...more
mortgage
September 22, 2026•2 min read
Business Owners With Strong Cash Flow Are Still Getting Denied Mortgages and Here Is Why
Tax deductions reduce qualifying income under traditional guidelines. Nicole and Robert Love explain bank statement loans. ...more
mortgage
September 21, 2026•2 min read
Being Told Your Income Does Not Qualify for a Mortgage May Not Be the Whole Story
How income is evaluated matters as much as how much you earn. Nicole and Robert Love explain non-QM options now. ...more
mortgage
September 15, 2026•2 min read
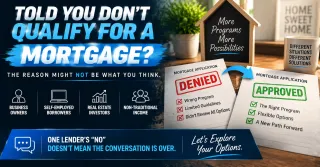
Being Told You Do Not Qualify for a Mortgage Does Not Always Mean You Cannot Qualify and Here Is Why
One lender's no isn't the final answer. Nicole and Robert Love explain why the program matters as much as finances. ...more
mortgage
September 15, 2026•2 min read
Mortgage Calculator
Estimate your monthly payment and see how a Non-QM loan could
work for your home or investment property.
| Year | Interest | Principal | Balance |
|---|
Quick Links
About Us
Blogs
Programs
